
What Is a Lopsided Deal in Fix and Flip?
Share the post:
Share the post:
Not all flips are created equal. Some are clean, cosmetic rehabs—new floors, fresh paint, updated fixtures—and others are full-blown rebuilds that test an investor’s skill and patience.
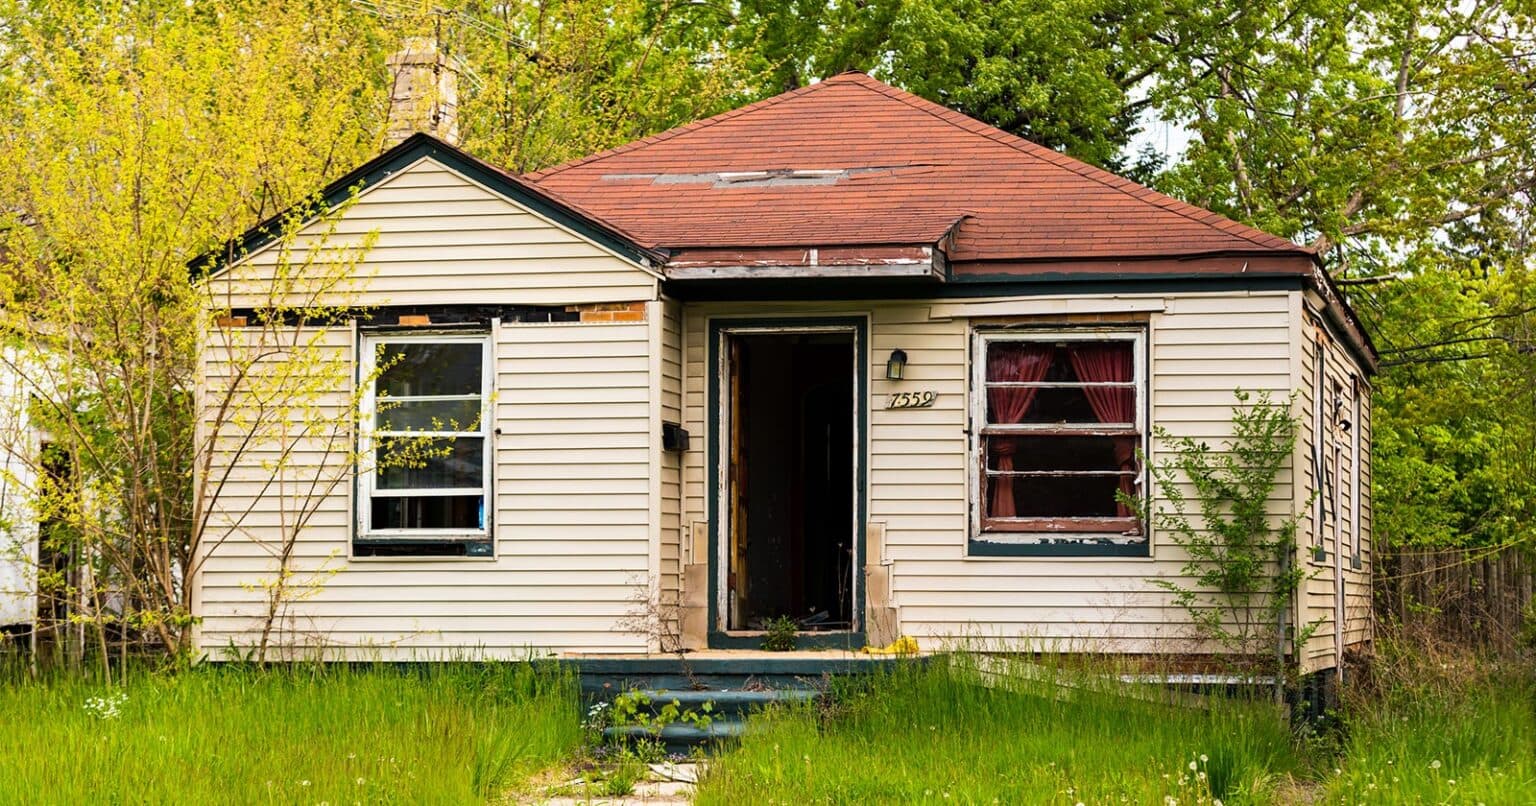
But every so often, a deal comes along where the rehab budget outweighs the purchase price. Maybe you’re buying a distressed property for $100,000, but the renovation will cost $150,000 or more.
That kind of setup is what the industry calls a “lopsided deal.”
These projects can be risky, but also extremely profitable when done correctly. Understanding how lenders view these deals, when they can work, and how to approach them strategically can help you turn a seemingly “imbalanced” opportunity into a success story.
At Finance of America Commercial, we regularly evaluate Fix and Flip projects that don’t fit the cookie-cutter mold. Here’s how to recognize a lopsided deal, why it happens, and what to consider before taking one on.
A lopsided deal occurs when the cost to renovate a property is greater than the price you paid for it.
This isn’t automatically a red flag, but it does require extra scrutiny.
Most traditional lenders are more comfortable when renovation costs are less than or equal to the purchase price. It signals a more stable deal structure with lower risk exposure. When the rehab cost exceeds the acquisition price, it can raise questions about feasibility, value, and execution.
Example:
At first glance, this looks heavily weighted toward construction. But if the numbers work—and you can justify the scope, experience, and ARV—this deal could still be profitable and fundable.
There are several reasons why the rehab cost might exceed the purchase price, and not all of them are bad. In many cases, it simply means you’ve found a property in major disrepair that needs a complete transformation.
In other words, lopsided doesn’t always mean bad, it just means more complex.
They absolutely can, but they require experience, precision, and the right lender.
A successful lopsided deal typically depends on:
If the project pencils out financially and the investor has a solid track record, lenders like FACo can structure the loan appropriately—often based on loan-to-cost (LTC) rather than just purchase price.
Here at FACo, we understand that not every property fits a “standard” model. Lopsided deals can make financial sense when the numbers and strategy align.
1. We Evaluate by Loan-to-Cost (LTC)
Instead of capping leverage strictly on the purchase price, we evaluate the total project cost (purchase + rehab). This allows us to fund deals where renovation represents the majority of the investment.
For example:
2. We Focus on Borrower Experience
When a project is heavily rehab-driven, experience is key. Lenders need confidence that you can execute a large renovation efficiently and manage contractors, inspections, and budgets.
3. We Require a Detailed Scope of Work (SOW)
A line-item budget, timeline, and material breakdown are essential. The more comprehensive your documentation, the smoother the underwriting process will be.
4. We Verify ARV Through Appraisal
Appraisers review your SOW and local comps to validate your projected after-repair value. If the ARV supports the total cost, the deal may still work despite being “lopsided.”
5. We Provide Flexible Draw Schedules
Because heavy rehabs require more capital early on, FACo can tailor draw schedules to align with project phases—so you always have liquidity when it matters most.
A heavily rehab-weighted project introduces higher risk: more contractors, more moving parts, and more ways for timelines or budgets to slip.
That’s why lenders like FACo typically prefer seasoned investors with at least 3-4 prior properties for these deals. Experienced flippers understand:
If you’re newer to investing, you don’t have to avoid these deals altogether, but you may need to partner with a more experienced borrower or start with smaller, cosmetic rehabs first. Once you’ve built a proven track record, lenders will be far more open to funding ambitious, high-rehab projects.
For most fix-and-flip loans, lenders assess leverage based on loan-to-value (LTV) or loan-to-cost (LTC) ratios.
In a lopsided deal, LTV can be misleading because the property’s as-is value is low, but the total project cost (and ARV) justifies the higher rehab spend. That’s where LTC becomes a more accurate benchmark.
LTC Formula:
LTC = (Loan Amount ÷ Total Project Cost) × 100
For example:
If your total project cost is $300,000 and your loan amount is $255,000, your LTC is 85%—well within standard lending thresholds.
By focusing on LTC, lenders can responsibly finance projects that might look unbalanced on paper but make strong financial sense in practice.
Not every high-rehab project is fundable or advisable. Be cautious if:
In these cases, the risk outweighs the potential reward. It’s better to walk away than to tie up capital in a deal that doesn’t cash flow or sell profitably.
If you’re submitting a lopsided deal for financing, preparation is everything. Here’s what helps your case:
The more detailed your package, the more likely your lender will see the project’s potential, rather than its risk.
At FACo, we know not every deal fits into a neat box. Our underwriting team specializes in evaluating value-add projects where experienced investors can turn challenging properties into profitable outcomes.
We offer:
Whether your project is cosmetic or complex, our goal is the same: to fund deals that make sense and help investors scale sustainably.
A lopsided deal isn’t automatically a bad deal. When managed properly, it can be one of the most lucrative types of fix and flips—transforming distressed assets into high-value properties.
The key is preparation, experience, and a lending partner who understands the numbers behind the story.
At FACo, we look beyond the surface. If your project’s total cost aligns with its ARV and your team has the experience to execute, we can structure funding that works for both sides.
Because the best flips aren’t always the simplest; they’re the ones where the investor sees potential where others see problems.
Explore your next opportunity with confidence. Visit our homepage or check out our Fix & Flip Loans to learn how we help fund projects of every shape, size, and scope.
A lopsided deal in fix and flip real estate occurs when a property's renovation costs exceed its purchase price. For example, an investor might purchase a distressed property for $100,000 and spend $150,000 on repairs. Although these projects involve higher renovation expenses, they can still offer profitable investment opportunities when the after-repair value (ARV) supports the total project cost.
Yes, a lopsided fix and flip deal can be profitable if the property's projected resale value exceeds acquisition, renovation, financing, holding, and selling costs by a sufficient margin. Investors should carefully evaluate comparable sales, contractor estimates, and local housing demand. A strong after-repair value and realistic renovation budget are essential for determining whether a heavy rehab investment makes financial sense.
Lenders typically evaluate lopsided fix and flip projects by examining the total project cost, after-repair value, borrower experience, and renovation scope. Because rehabilitation expenses exceed the purchase price, lenders may place greater emphasis on loan-to-cost (LTC) ratios and detailed construction budgets. Finance of America Commercial (FACo) considers these factors when assessing financing opportunities for complex renovation projects.
The loan-to-cost (LTC) ratio measures the loan amount as a percentage of the property's total acquisition and renovation costs. For example, a $255,000 loan on a project costing $300,000 represents an 85% LTC ratio. FACo's outlined approach to qualifying lopsided deals includes financing of up to 85% LTC, depending on borrower experience, market conditions, and underwriting requirements.
After-repair value (ARV) represents a property's estimated market value after all planned renovations are completed. For lopsided fix and flip projects, ARV is especially important because significant rehabilitation costs must be justified by the property's potential resale price. Lenders use appraisals, comparable sales, and renovation plans to evaluate whether the projected ARV supports the requested financing.
First-time investors may face additional challenges when seeking financing for lopsided fix and flip projects because extensive renovations require strong project management skills. Lenders often prefer borrowers with a proven track record in property rehabilitation. Beginners may improve their financing prospects by partnering with experienced investors, hiring qualified contractors, and presenting a detailed renovation and financial plan.
Financing a heavy renovation property generally requires a detailed scope of work (SOW), itemized construction budget, contractor estimates, project timeline, and property appraisal. Lenders may also request comparable sales, proof of financial reserves, building permits, and documentation of previous investment experience. Providing comprehensive information helps lenders assess construction risks and determine whether the project qualifies for fix and flip financing.
Investors can reduce the risks of lopsided fix and flip deals by conducting thorough property inspections, obtaining accurate contractor bids, and maintaining contingency reserves for unexpected expenses. Using conservative after-repair value estimates and realistic renovation timelines is equally important. Working with an experienced construction team and a lender familiar with heavy rehab financing can help investors manage project costs and avoid costly delays.
Authored by Bianca Montalvo
SEO copywriter and strategist
This content is for informational purposes only and should not be construed as investment or legal advice. Neither the author of this content nor Roc360 assumes any liability for actions taken or not taken based on information contained herein. Investments involve risk, including potential loss of principal. You should consult a qualified professional before making financial decisions.
Table of contents Rent vs. Sell Calculator Weighing the Pros & Cons of Renting…
Table of contents Top 5 Places to Invest on the East Coast Rent or…
Table of contents Is it Better to Build New Construction or Renovate Existing Homes?…
